September 3,2014
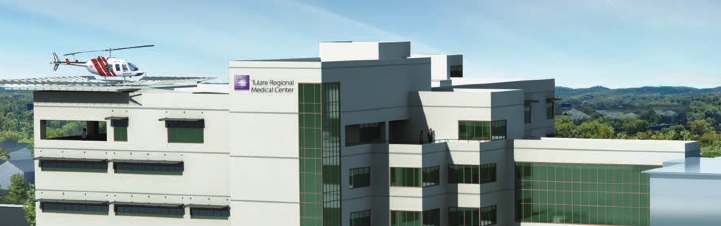 In a reversal from only a few months ago Fitch Ratings has affirmed the ‘B’ rating on $15,230,000 series 2007 fixed rate bonds issued by the Tulare Local Health Care District d/b/a Tulare Regional Medical Center (TRMC).In addition Fitch said the Rating Watch Negative has been removed and the Rating Outlook is Stable.
The Fitch report says there are new signs of a “dramatic turnaround “ although financials remain weak. The report does not delve into the district’s need to raise more capital to finish its delayed tower project that has been estimated at needing $40 million more to complete.
The latest TRMC financial report for July shows continuing operational issues with acute patient days revenue for the month 23% lower than July 2013.
Here are Fitch’s comments.
Fitch said the removal from Rating Watch Negative reflects growing clarity and progress on construction plans achieved over the last six months. A settlement was reached with the previous contractor in July 2014. A new team has been put in place under HealthCare Conglomerate Associates’ (HCCA) leadership, and a completion plan has been established. Currently, TRMC is evaluating various funding options, but no new debt is expected at the TRMC level.
SIGNS OF TURNAROUND: The Stable Outlook reflects the dramatic turnaround in operating and financial performance since Fitch’s last review in February 2014. TRMC posted an operating loss of $3.9 million through the six months ended Dec. 31, 2013, but a positive operating income of $1.6 million in the second half of the year. Improved operating margin of negative 3.3% at fiscal year ended (FYE) June 30, 2014 (unaudited interim results) was attributable to revenue enhancement as well as expense reduction initiatives.
Fitch believes the positive trend over the last few months indicates performance improvement plans taking hold and signal recovery.
LIQUIDITY REMAINS WEAK: TRMC’s liquidity position remains very low, albeit slightly improved from one year ago. Unrestricted cash and investments were $10.4 million at FYE 2014 was over 20% increased year-over-year, and equated to 57.3 days cash on hand, 4.1x cushion ratio, and 57% cash to debt.
DISPUTE WITH TRUSTEE: By letter dated Aug. 4, 2014, the US Bank, as Trustee, issued a notice to TRMC asserting the occurrence of various defaults and Events of Default (EoD) under the Indenture, including failure to achieve the required long term debt service coverage ratio for fiscal years 2012 and 2014. TRMC has denied the existence of any defaults or EoD and the Trustee has withdrawn the Notice of Default by letter dated Aug 8. At this time, TRMC has made all required payments under the indenture. Fitch expects that this matter will be resolved without any negative impact to bondholders or the credit profile of TRMC.
CLARITY ON PROJECT FUNDING: Considerable amount of uncertainty around the timing and funding sources remain, although meaningful progress has been made over the last six months. Fitch believes that the hospital can continue to operate without completion of the project over the near term. Further, additional debt funding secured by the revenues of the hospital is not expected to be pursued over the near term.
Tulare Local Health Care District, d/b/a Tulare Regional Medical Center owns and operates a 112-bed hospital in the city of Tulare, California. Total operating revenue in FYE June 30, 2014 was $68.6 million (exclusive of tax revenues related to GO bonds debt service). Since January 2014, TRMC has been managed by HealthCare Conglomerate Associates under a management agreement.
Construction Plans Developing
TRMC has a construction project in progress featuring a 24-bed emergency department, a new diagnostic department, a 16-bed obstetric unit, four surgery suites, and 27 new private patient rooms meeting seismic requirements. This new expansion tower was initially slated to open October 2012, but suffered disruptions due to concrete delamination issues and ensuing conflicts with the contractors.
Over the last six months, TRMC was able to reach a settlement agreement with the previous contractors and put a makeup schedule and budget in place. The completion of the project is now pending a funding source, with several options currently under evaluation. Fitch assumes that the ultimate decision will not have a material impact on TRMC’s solvency, and will evaluate any impact of funding sources after plans are finalized and disclosed.
Signs of Turnaround
TRMC posted a loss of $2.3 million (negative 3.3% operating margin) in fiscal 2014, which is significantly improved from a $3.9 million loss (negative 12% operating margin) through the six months ended Dec. 31, 2013. Similarly, operating EBITDA margin improved from a negative 3.8% to a positive 4.2%. Management’s initial goal was to breakeven in calendar year 2014. Given the $1.6 million operating income generated in the six months ended June 30, 2014, Fitch believes TRMC is on track to meet its targets.
Under a new leadership team from HCCA, the performance improvement plan largely focuses on putting sustainable operating structures in place, with a two-pronged approach at enhancing revenues and reducing expenditures. With inpatient volume continued to weaken, fiscal 2014 marked the first year of growth in outpatient surgeries and emergency department visits in over three years. Fitch also believes MediCal expansion will also be beneficial for TRMC in generating additional outpatient traffic.
Weak Liquidity
Liquidity showed modest growth in fiscal 2014, following four years of rapid declines driven by IT investments, other capital spending, and negative cash flow. Unrestricted cash and investments totaled $10.4 million at June 30, 2014 compared to $8.7 million at FYE 2013 and $24.4 million at FYE 2010. Days cash on hand of 57 days, cushion ratio of 4.1x, and cash to debt of 57% remain weak compared to Fitch’s median for below investment-grade ratings. Continued expense control and improvement in revenues should improve overall cash flow and slowly rebuild the balance sheet. While not expected, demand on unrestricted liquidity to support operations or fund the construction project would be viewed negatively.
